Should I lower my coaching prices? A break-even check
Do not lower your coaching prices simply because sales are slow. If you are asking “should I lower my coaching prices?”, first compare how many clients your current and proposed prices need to cover the same costs. Then check whether you can realistically serve that many. A lower price that needs more clients than you can accommodate cannot cover those costs. A price that fits your capacity still needs enough paying buyers.
This check is for a defined one-to-one coaching offer. It separates a question you can calculate, whether the proposed price can cover your costs, from one arithmetic cannot answer: whether lowering the price will bring more clients.
Check what slow coaching sales actually means
Before changing the fee, look at the most recent enquiries and offers for this particular service. Record what happened and what prospective clients actually said. Keep your interpretation separate from their words.
| What you observe | What to investigate |
|---|---|
| Few suitable people enquire. | Who is seeing the offer and whether they are looking for this kind of support. |
| People enquire but never receive a clear offer. | Whether they understand the work, the price and the next step. |
| Suitable buyers receive the offer and decline. | Their stated reasons, including total affordability, payment timing, fit or uncertainty about the support. |
None of these observations proves what a different price would do. “Too expensive” deserves attention, but it does not tell you how many additional people would buy at a lower fee. Nor does a quiet week establish that your price is wrong. Use the comparison below to check feasibility before you rely on an increase in sales.
Compare the same coaching offer at both prices
Write down the sessions, session length, preparation, between-session support and period covered. Hold those details steady for this comparison. Cutting the fee while adding extra support changes both the price and the work you must deliver.
For the example below, we define one unit as one client receiving one month of the same one-to-one service. That client-month is our editorial application of a general business formula. It is not an SBA definition of coaching, and it does not mean you must find a new client every month. Continuing clients can occupy those places.

If you also change the number of sessions or the support included, calculate the revised offer separately. You would be assessing a different service, so the unchanged-cost comparison would no longer describe it.
Gather your monthly costs and realistic client capacity
Use your own bills, payment records and calendar. The SBA’s break-even guidance uses fixed costs, selling price and variable cost per unit. Its calculator uses monthly inputs and describes a single product or service. Keep the period and service consistent throughout your calculation.

| Input | What to enter |
|---|---|
| Current and proposed price | The amount charged for one client-month of the defined service. |
| Monthly fixed costs | Costs that remain the same at the client numbers you are comparing. |
| Variable cost per client-month | Costs that increase with each client served. Recalculate them at each price if necessary. |
| Current paid client-months | The number actually buying this service in the period, rather than enquiries or unaccepted proposals. |
| Sustainable capacity | The client-months you can deliver after allowing for preparation, follow-up, administration and other commitments. |
| Owner compensation | State explicitly whether your cost total includes it. The worked example below excludes it. |
Classify expenses using their actual terms. A flat software subscription may be fixed within its plan limits. A genuinely per-client expense may be variable. If a bill combines a fixed base and usage charges, separate those parts where possible, as SBA recommends for mixed costs. Percentage-based payment fees can change when the price changes, so do not automatically copy the same variable-cost figure into both columns.
Check the price against actual paid records, including concessions, rather than relying only on the amount on your sales page. Keep the payment period aligned with the service period. A whole three-month package fee divided into one month of fixed costs will give a misleading comparison.

Capacity also needs a reality check. Count the full commitment per client, not just the calls. Check the busiest weeks as well as the monthly total. An empty appointment slot is usable only if you also have time to prepare, follow through and keep the practice running.
Calculate break-even at the current and lower price
SBA defines break-even as the point where total revenue equals total cost. Its formula is:
Break-even units = fixed costs ÷ (price per unit − variable cost per unit).
For our client-month comparison, price minus variable cost is the amount each client contributes toward fixed costs. Divide monthly fixed costs by that amount. Then round upward to a whole client: 4.29 client-months means you need five to cover the modeled costs.
For a short explanation of the general arithmetic, Chegg’s lesson below covers break-even analysis. It explains the formula, rather than coaching demand or whether you should discount.
Every dollar amount below is hypothetical. These are not market rates or a recommended discount. Assume monthly fixed costs of $1,200, variable costs of $20 per client-month at either price, four currently paid client-months and capacity for five. Each column assumes all client-months are sold at that column’s price. Owner compensation and taxes are excluded. The $20 is an assumed total variable cost, not a quoted payment-processing fee.
| Measure | Current price | Proposed lower price |
|---|---|---|
| Price per client-month | $300 | $240 |
| Monthly fixed costs | $1,200 | $1,200 |
| Variable cost per client-month | $20 | $20 |
| Contribution per client-month | $300 − $20 = $280 | $240 − $20 = $220 |
| Unrounded break-even client-months | $1,200 ÷ $280 = 4.2857… | $1,200 ÷ $220 = 5.4545… |
| Whole client-months needed to cover costs | 5 | 6 |
| Result at four clients, before owner pay and taxes | -$80 | -$320 |
| Result at five-client capacity, before owner pay and taxes | +$200 | -$100 |
At four clients, the current price produces $1,200 in revenue against $1,280 in modeled costs: $1,200 fixed plus four lots of $20. The lower price produces $960 against those same costs. At full five-client capacity, the lower price still leaves a $100 shortfall. Filling the calendar would not solve this example’s cost problem.

The proposed price is 20% lower, but that does not establish a universal 20% increase in sales needed. Contribution per client and whole-client rounding determine this comparison. Here the requirement moves from five client-months to six, while the coach currently sells four.
With positive fixed costs, a price equal to or below variable cost leaves no finite break-even client count in this simple model. Each additional client provides nothing toward fixed costs, or increases the shortfall.
Use the result to decide what to investigate next
| Your result | Practical implication |
|---|---|
| The lower price needs more clients than you can serve. | The proposed cut cannot cover the included costs at that capacity. Reconsider the cut, costs or service design before relying on more sales. |
| The requirement fits capacity but exceeds present sales. | The price is feasible in the model only if enough additional places sell. Identify evidence for that increase before depending on it. |
| Present sales already meet the lower-price requirement. | The included costs could be covered if those sales continue. Check owner compensation and the reason for reducing the price before deciding. |
Even the $200 remaining at the current price in our example does not show that the coach can pay themselves what they need. It is simply what remains after the costs we included. Use the separate guide to setting a coaching revenue target for the broader income-planning question.
If the proposed price passes the capacity check, return to buying evidence. Review comparable prospects and their stated reasons for declining. Our coaching package price-testing guide explains how to organize that work. This calculation cannot predict demand, establish a market rate or guarantee that a cut will work.
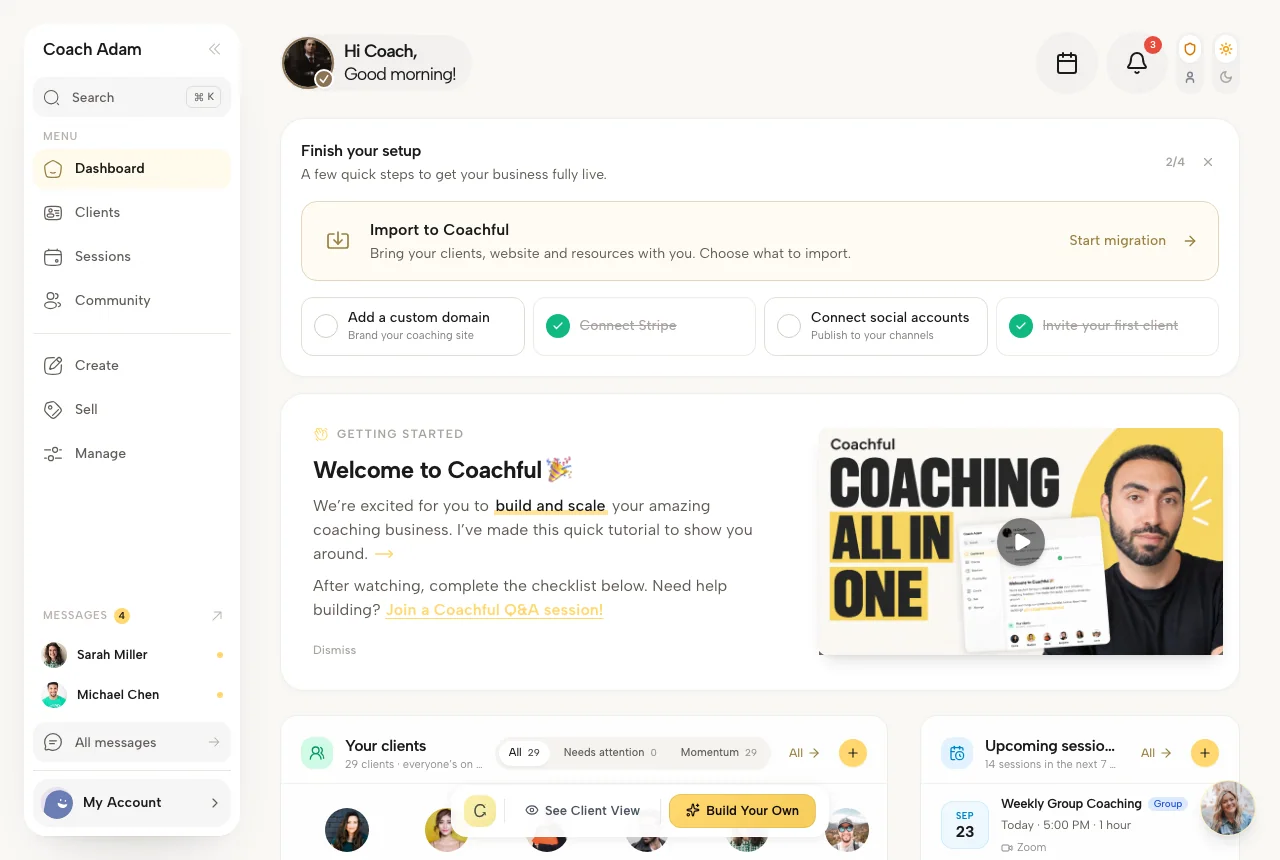
Keep the offer and payment evidence organized in Coachful
Coachful publishes this guide. For implementing a clearly defined offer, Coachful brings packages and payments into the same platform: its coaching payment software supports one-time payments, subscriptions, payment plans and invoices. The reviewed Bundles and Invoices views above show the offer and payment records you can keep organized.
Coachful scheduling supports availability rules and buffers, and video calls are included in the coaching-software subscription. You do not need to add a separate video-service subscription as a required cost for that setup. Use your actual subscription and processing costs in your own comparison.
Start with a spreadsheet if you only need to compare two prices. Coachful’s useful next step is organizing the offer, payments and bookings once you have made the decision. Keep the break-even calculation and your assumptions alongside those records.
Frequently asked questions about lowering coaching prices
Will lowering my coaching price get more clients?
The calculation cannot tell you. It shows how many clients a given price needs to cover specified costs. Whether more people will buy requires evidence from suitable prospective clients and actual purchases. Slow sales alone do not establish that price is the cause.
How many more clients would I need after a price cut?
Run the formula at both prices and round each result upward. In our hypothetical example, the requirement rises from five client-months at $300 to six at $240. Because current sales are four, reaching the lower-price requirement would mean selling two additional client-months. Your costs and prices may produce a different result.
What if the lower price fits my capacity?
That removes one obstacle, but does not establish demand. Compare the required number with present paid clients and assess whether you have evidence for filling the gap. Also check what the cost total includes. A price can cover business expenses while leaving too little for owner compensation.
Does breaking even include paying myself?
Only if the costs you included account for that compensation. Our example explicitly excludes owner pay and taxes. Its positive $200 result at five clients and the current price is therefore not a funded personal-income target. State your assumptions before interpreting your own result.
Can I use a multi-session package in this calculation?
Yes, if you align the unit, delivery period and costs. Our example counts client-months. Do not substitute a whole multi-month package price while keeping only one month of costs. Calculate the same service over a consistent period at each price, and account for the work already committed across those months.
Before changing the fee: write the current price, proposed price, relevant costs, present paid client-months and sustainable capacity on one page. Calculate both requirements. If the lower price needs a calendar you cannot deliver, revise the proposal before offering it.