Is Life Coaching Covered by Insurance? HSA, FSA and EAPs
Usually no. Is life coaching covered by insurance in the US? Almost never, because health insurers pay for medical care that diagnoses or treats a condition, and life coaching is not health care: there is no diagnosis, no licensed provider and no billing code for it. The real exceptions are coaching your employer pays for, a few coaching services built into employee or health programs, and, separately, therapy, which most plans do cover.
That answer disappoints people, so the useful part is what to do next. Below is how each payment route works (health insurance, HSA and FSA cards, superbills, EAPs, Medicare and employers), where the line sits between coaching and covered care, and how to keep the cost of a coach manageable if you pay yourself.
The quick answer, question by question
| Question | Short answer | Who to ask |
|---|---|---|
| Does health insurance cover life coaching? | Usually no. Coaching is not medical treatment. | Your insurer's member services line |
| Do life coaches take insurance? | Almost never. There is nothing a life coach can legitimately bill. | The coach, on the discovery call |
| Can I pay with an HSA or FSA? | Generally no for life coaching. These accounts pay for medical care as the IRS defines it. | Your plan administrator |
| Can I get a superbill? | Not a valid one. Superbills carry diagnosis and procedure codes from a licensed provider. | Your insurer, before you pay |
| Does an EAP cover it? | Sometimes, if your employer's program includes coaching. Most EAPs center on short-term counseling. | Your HR team or EAP phone line |
| Will my employer pay? | Often, for coaching tied to your work. | Your manager or learning and development team |
| Does Medicare cover it? | Not life coaching. Medicare covers a diabetes prevention program, and CMS has proposed paying for health coaching under a clinician's supervision. | Medicare or your plan |
| Is therapy covered instead? | Usually yes. Marketplace plans cover psychotherapy and counseling. | Your insurer |
Why health insurance doesn't pay for life coaching
Insurance pays for a service when three things line up: a licensed provider, a diagnosis that makes the service medically necessary, and a recognized code to bill it under. Life coaching has none of the three. Anyone can call themselves a life coach in the US, because no state licenses the title (our guide to whether a life coach needs a license explains why). A coach doesn't diagnose, and the work is aimed at goals you choose, such as a career change, a calmer week or a stalled decision, rather than at an illness.
The IRS draws the same line for tax purposes, and its definition is a good way to see how insurers think. IRS Publication 502 says medical expenses are "the costs of diagnosis, cure, mitigation, treatment, or prevention of disease," and that they don't include expenses that are "merely beneficial to general health" (IRS Publication 502). Coaching that helps you feel more on top of life sits on the general-health side of that line.
None of this means coaching doesn't work. It means it is bought the way you buy a course, a personal trainer or a career adviser: with your own money or your employer's. If you are weighing whether that spend is worth it, our guide to whether a life coach is worth it goes through the research and the sums.

Do life coaches take insurance?
A legitimate life coach will tell you no. If someone selling "life coaching" says they can bill your insurer, ask what they would bill and under whose license. There are only a few honest explanations:
- They are also a licensed therapist, and what they would bill is therapy, with a diagnosis, notes and the rules that come with it. That can be exactly what you need, but it is therapy, not coaching. Our guide to life coach vs therapist explains the difference.
- They are a health coach working inside a medical practice, where a physician or other practitioner bills for supervised services. A self-employed life coach can't do this on their own.
- They mean an employer or program pays, not your health plan.
If the answer is vague, or involves putting a diagnosis on paperwork so a claim goes through, walk away. Submitting a claim for a service that wasn't medical care can cause real problems for you, not only for the coach.
Can you use an HSA or FSA for life coaching?
Generally no. Health savings accounts and health flexible spending arrangements pay for "medical care" as defined in the tax code, the same definition Publication 502 explains (IRS Publication 969). Life coaching for personal goals doesn't meet it.
The IRS's own examples show how narrow the exceptions are. Its FAQ on nutrition, wellness and general health says nutrition counseling and weight-loss programs count as medical expenses "only if" they treat "a specific disease diagnosed by a physician," and that exercise recommended by a doctor still doesn't count when it is only for general health (IRS FAQ). The same FAQ says therapy to treat a diagnosed mental illness is a medical expense, while marital counseling is not.
Getting this wrong costs money. An HSA withdrawal that isn't for a qualified medical expense is added to your income and, in most cases, hit with an additional 20 percent tax. A health FSA needs a written statement from an independent third party showing the expense was incurred. Before you tap either account for anything coaching-related, ask your plan administrator in writing, and talk to a tax professional if the amount matters to you.
A card payment that goes through at checkout doesn't settle the question. The account rules still apply afterwards, and an FSA can ask you to prove what the money paid for.
What about a superbill?
A superbill is an itemized statement a provider gives you so you can ask your insurer to reimburse an out-of-network visit. It lists the provider's credentials, the diagnosis code and the procedure code. A life coach has no diagnosis to give and no license to bill under, so there is no honest superbill for life coaching. A plain receipt or invoice is still worth keeping, because an employer reimbursing you for work-related coaching will usually want one.

Where coaching is covered, or paid for by someone else
This is where the money actually comes from when you don't pay yourself.
| Route | What it pays for | What to check |
|---|---|---|
| Your employer | Leadership, career and performance coaching tied to your job | Learning budgets, manager approval, whether the coach must be on an approved list |
| Employee assistance program (EAP) | Short-term counseling, referrals and follow-up; some employers add coaching | Whether coaching is in your EAP's menu, and how many sessions |
| Medicare | The Medicare Diabetes Prevention Program, about a year of lifestyle sessions for people at risk of type 2 diabetes | Whether you qualify and which suppliers run it near you |
| A clinic or health system | Health coaching delivered as part of your care, under a clinician | Whether your doctor's practice offers it |
| Your health plan's preventive benefits | Diet counseling for adults at higher risk of chronic disease, obesity screening and counseling, from an in-network provider | Your plan's preventive services list |
Employers are the biggest payer by far. In the 2023 ICF Global Coaching Study, coach practitioners said that, on average, 57 percent of their clients were sponsored, meaning someone other than the client paid (ICF, 2023). If your goal touches your work, a short written case to your manager is often the cheapest route to a coach.
EAPs are worth one phone call. The US Office of Personnel Management describes an EAP as a voluntary, work-based program offering free and confidential assessments, short-term counseling, referrals and follow-up (OPM). Counseling is the core. Coaching depends entirely on what your employer's program has bought, so ask the EAP line directly.
Medicare has one real coaching benefit. The Medicare Diabetes Prevention Program is covered under Part B as a preventive service: 16 weekly core sessions, then monthly maintenance sessions, for people at risk of type 2 diabetes (CMS). Separately, in July 2026 CMS proposed paying for health and well-being coaching codes when certified coaches deliver them under a billing practitioner's supervision. That proposal was not final as of October 2026, and it concerns health coaching inside medical care, not life coaching. Our guide to whether a health coach can bill insurance covers it in detail.
Your plan's preventive benefits are counseling, not coaching. HealthCare.gov lists diet counseling for higher-risk adults and obesity screening and counseling among the preventive services Marketplace plans must cover, at no cost from an in-network provider in most cases (HealthCare.gov). If your goal is weight or eating, ask your doctor about these before paying anyone.
If what you need is covered care
Sometimes the honest answer to "will insurance pay for my coach?" is that you need something insurance does pay for. All Marketplace plans cover mental health and substance use services as essential health benefits, including psychotherapy and counseling, and limits on that care generally can't be stricter than limits on medical care (HealthCare.gov). Employer plans vary, so check yours.
See a licensed professional when:
- low mood, worry or panic is getting in the way of work, sleep or relationships most days;
- you are dealing with trauma, grief that won't shift, an eating disorder or substance use;
- you want a diagnosis, or medication, or someone to tell you what is going on;
- you have thoughts of harming yourself. In the US, call or text 988 to reach the 988 Suicide and Crisis Lifeline, any time.
Plenty of people do both: therapy through insurance for the clinical work, and a coach they pay for the practical goals. A good coach will welcome that arrangement and agree with you on what each one covers.

How to make life coaching affordable when you pay yourself
Most people who hire a life coach pay out of pocket, so it helps to know what normal looks like. These ranges come from Coachful's 2026 Coaching Business Report, which compiles PayScale data, practitioner reports and a small verified sample of published rates (coachingrates.com).
| What you buy | Typical price | Source behind the range |
|---|---|---|
| One life coaching session | $75 to $200 | PayScale and practitioner reports |
| Four-week starter, four sessions | $400 to $600 | Practitioner reports |
| Three months, eight sessions | $1,200 to $2,500 | Practitioner reports and a verified sample of published rates |
| Group coaching | $100 to $300 a month | Practitioner reports |
US dollars, Q2 2026. Practitioner figures are estimates, not study results. More detail is in our guide to how much life coaches charge.
Ways to bring the cost down without picking a bad coach:
- Ask your employer first, even for goals that seem personal. Confidence, boundaries and career direction usually affect work.
- Start with a short block. Four to eight sessions with a review point beats committing to six months up front.
- Try group coaching. A small group with weekly calls costs a fraction of one-to-one work and adds people working on the same thing.
- Ask about payment plans. Many coaches split a package into monthly payments.
- Check what happens between sessions. Messages, check-ins and a shared plan can make fortnightly sessions go as far as weekly ones.

Ask every coach the same few questions on the first call: what's included, what the agreement says about cancellations and refunds, and how they'd refer you on if what you need turns out to be therapy. Our questions to ask a coach before hiring has the full list, and is life coaching legit covers the warning signs.

Find a life coach on Coachful
Coachful runs a public coach directory at Find a Coach. You can search by topic, browse coaches or programs by category, such as mindset or lifestyle, or answer a short matching quiz that asks what you want to work on. Each coach lists their own approach, offers and prices, and you can book a discovery call to check the fit before you pay for anything. For a step-by-step approach, see how to find a life coach.


Are you a coach?
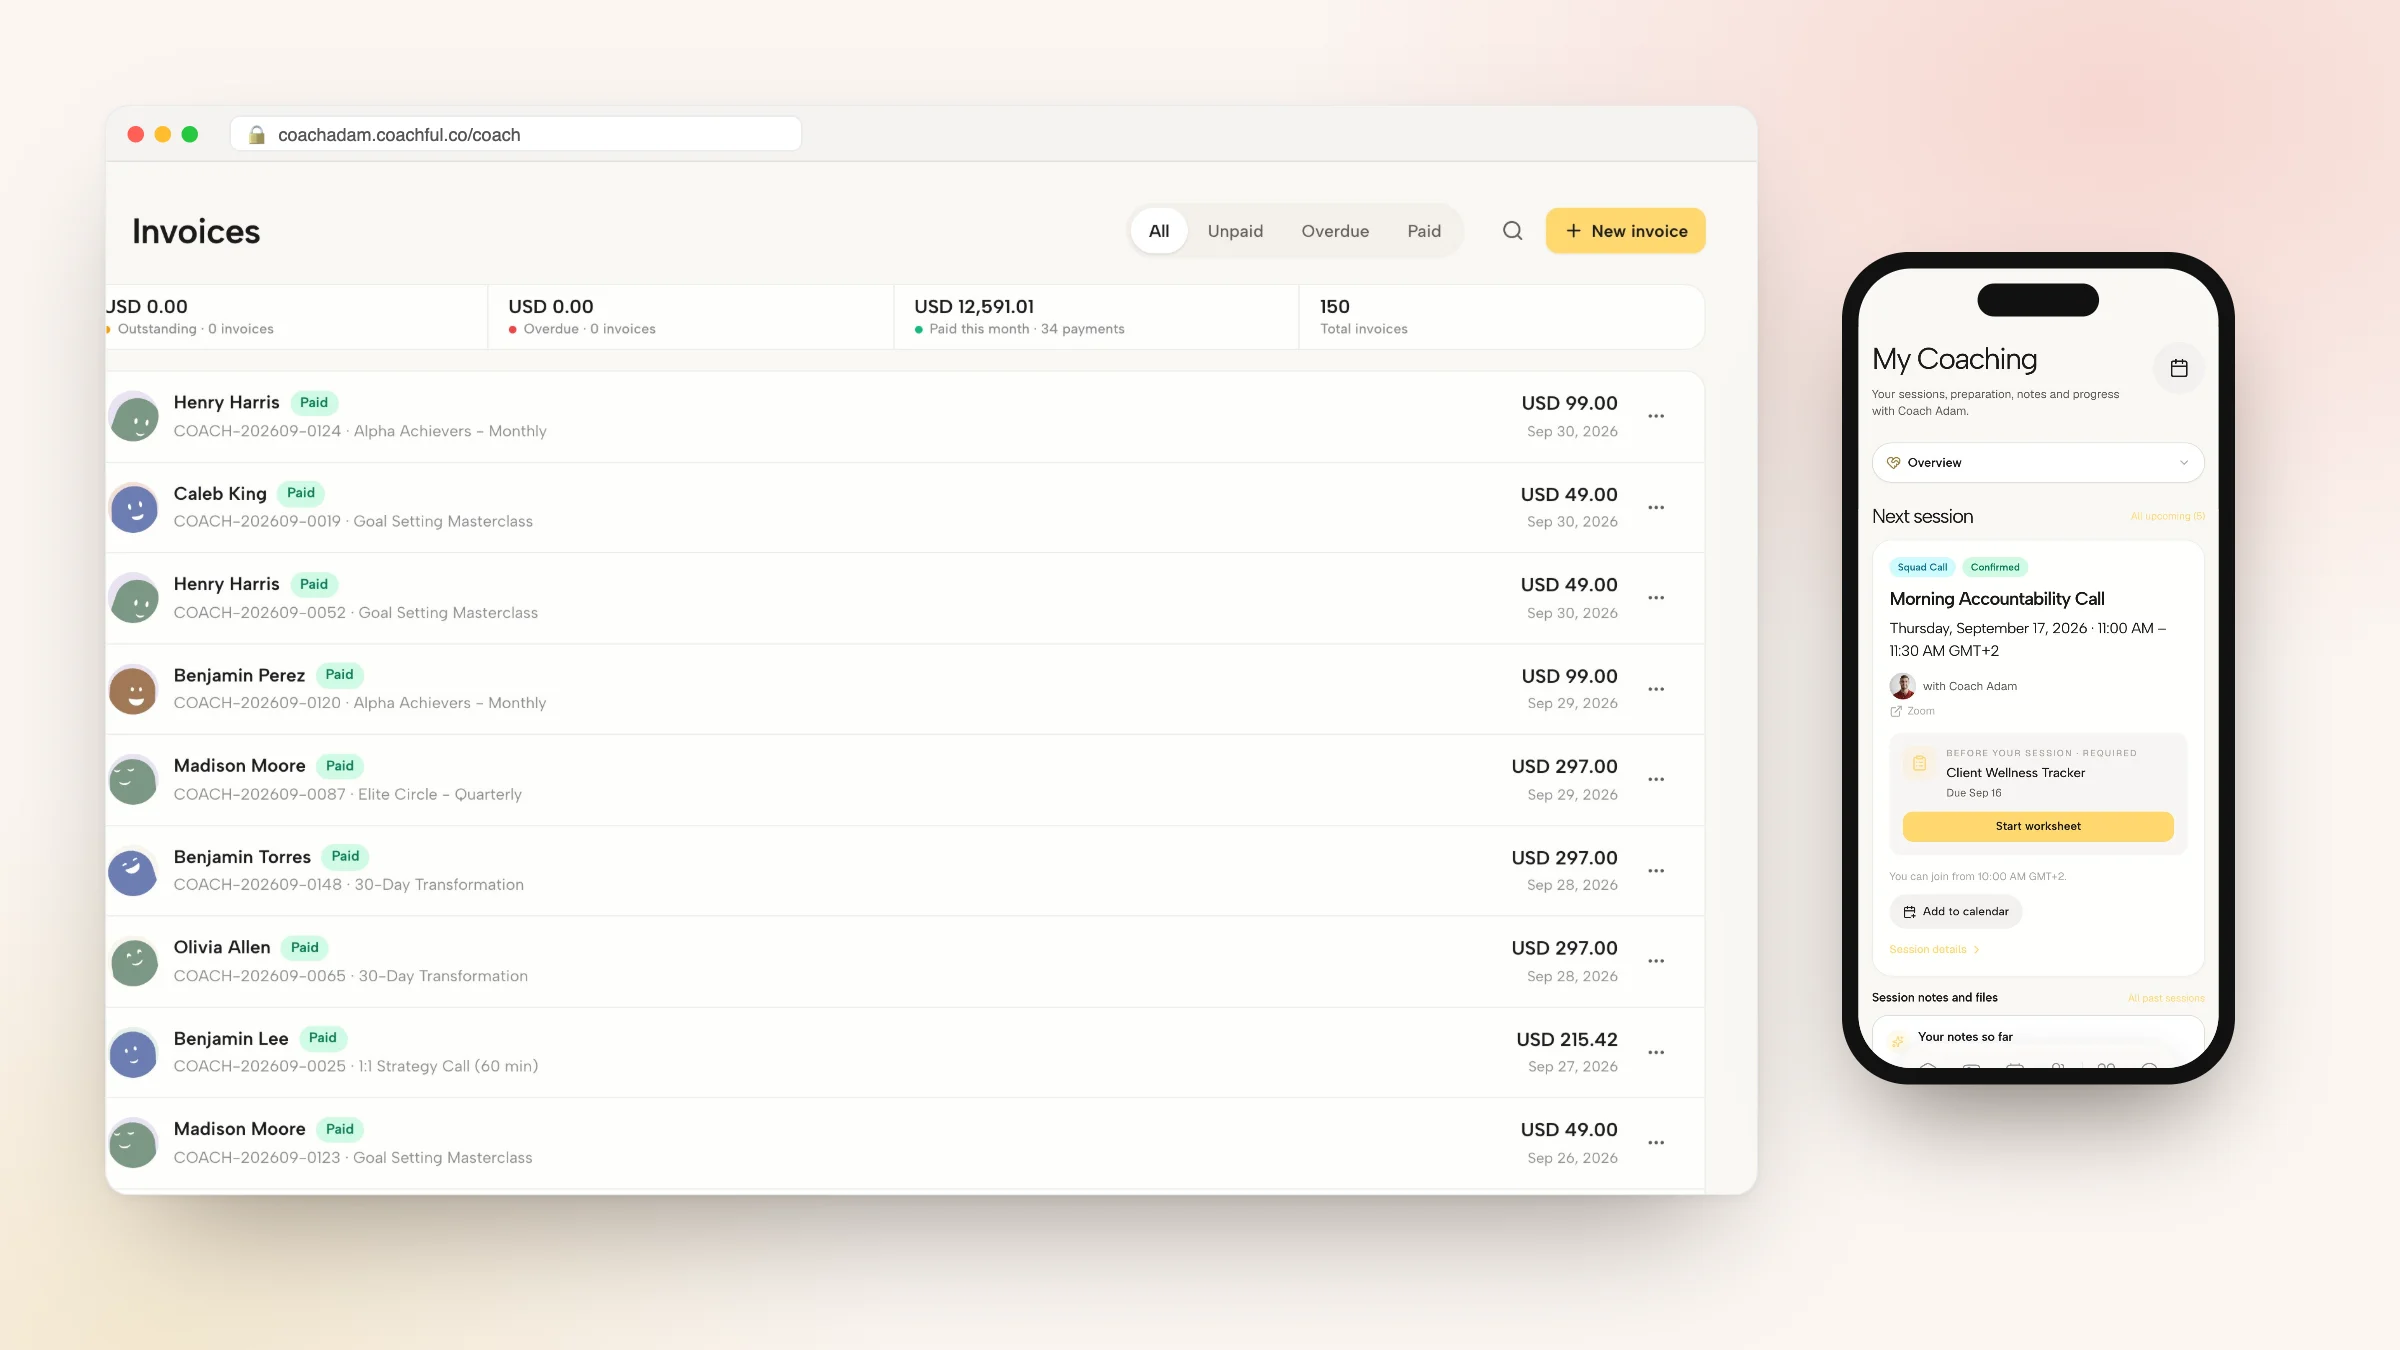
Clients will ask you about insurance, so put the answer on your website and in your agreement: coaching isn't billed to health insurance, and here is what employers often reimburse. Coachful runs booking, payments with invoices for every transaction, agreements and the client app for life coaches, and our team will build your coaching website for free on every plan through the free white-glove service.
Frequently asked questions
Is life coaching covered by health insurance?
Usually no. Health insurance pays for medical care from licensed providers, tied to a diagnosis and a billing code. Life coaching has none of those, so plans don't cover it. Employers, EAPs and some health programs pay for coaching outside your health plan.
Can a life coach bill insurance?
No. A life coach has no license to bill under and no diagnosis to submit. Only licensed providers bill health insurance. If a coach is also a licensed therapist, what they bill is therapy, which comes with its own rules and records.
Is life coaching HSA or FSA eligible?
Generally no. HSAs and health FSAs pay for medical care as the IRS defines it, and coaching for personal goals is general well-being. The IRS allows related programs, such as nutrition counseling, only when they treat a specific disease diagnosed by a physician. Ask your plan administrator before paying.
Can I get a superbill from a life coach?
Not a valid one. A superbill carries the provider's credentials, a diagnosis code and a procedure code so you can claim out-of-network reimbursement. A life coach can give you an invoice or receipt, which is what an employer usually needs for reimbursement.
Does an EAP pay for life coaching?
Sometimes. EAPs are built around free, confidential short-term counseling and referrals, and some employers add coaching to the menu. Call the number on your EAP materials and ask whether coaching is included and how many sessions you get.
Does Medicare cover life coaching?
No. Medicare covers the Diabetes Prevention Program, which uses lifestyle coaching for people at risk of type 2 diabetes. CMS has also proposed paying for health and well-being coaching under a clinician's supervision, but that proposal was not final as of October 2026 and doesn't cover life coaching.
How do I pay for a life coach if insurance won't?
Ask your employer, check your EAP, then look at group coaching or a short four-to-eight-session block. Typical life coaching runs $75 to $200 a session, with three-month packages around $1,200 to $2,500, from Coachful's 2026 Coaching Business Report.